Table of Contents
Few industries deal with cash flow swings quite like restaurants. Between seasonal slowdowns, unexpected equipment repairs, rising food costs, and the simple reality that revenue can vary significantly week to week, restaurant owners often need access to capital faster than traditional financing can provide. This is one of the main reasons Merchant Cash Advances (MCAs) have become such a common funding tool in the restaurant industry.
Why MCAs Are Popular Among Restaurant Owners
Speed. When a walk-in cooler breaks down or you need to restock before a holiday weekend, waiting weeks for a bank loan isn’t realistic. MCAs can often be approved and funded within a day or two.
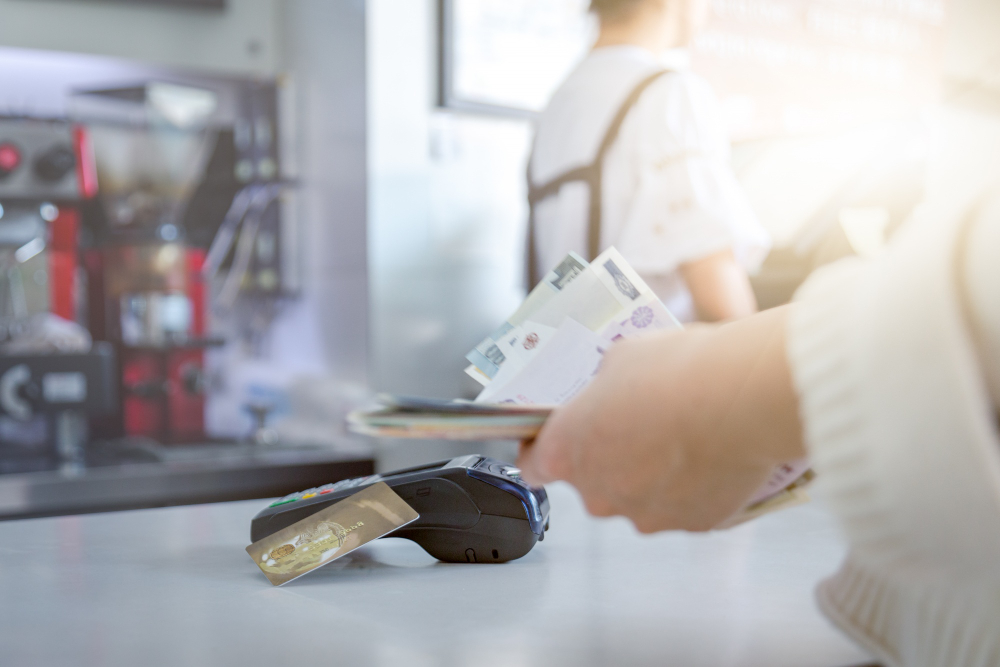
Revenue-based repayment. Restaurants typically have high transaction volumes via card payments, which makes them well-suited to MCA structures where repayment is tied to a percentage of daily card sales. During a slow week, the repayment amount adjusts down accordingly.
Accessible even with imperfect credit. Many restaurant owners — especially those who are newer or have had a difficult year — may not qualify for traditional bank financing. MCA approval focuses primarily on your sales history, making it accessible to a wider range of restaurant businesses.
Common Uses for MCA Funding in Restaurants
- Equipment repairs or replacement — ovens, walk-in coolers, POS systems
- Inventory and food cost management — especially ahead of busy seasons or holidays
- Renovations or refreshes — updating the dining room, kitchen improvements
- Bridging seasonal gaps — many restaurants experience predictable slow periods
- Payroll during transitions — covering staffing costs during a slow stretch or while hiring
What to Consider Before Applying
MCAs work best when there’s a clear plan for the funds and a reasonable expectation of how repayment will fit into your existing cash flow. Before applying, restaurant owners should consider:
- What’s the funding actually for? A clear purpose helps evaluate whether the cost makes sense relative to the benefit — for example, fixing essential equipment that’s currently costing you sales versus a “nice to have” upgrade.
- How does your card sales volume typically look? Since repayment is tied to sales, understanding your typical daily/weekly card revenue helps you gauge what repayment will look like in practice.
- Have you compared offers? Terms vary between MCA providers — sometimes significantly. Comparing multiple offers before committing can make a real difference.
How Tavrix Capital Helps Restaurant Owners
Rather than going directly to a single MCA provider, Tavrix Capital connects restaurant owners with multiple funding partners experienced in the food service industry. We review your situation — revenue, time in business, and what you need the funding for — and identify partners whose programs are likely to offer competitive terms for your specific business.
The application is simple and free, and there’s no obligation to accept any offer. For many restaurant owners, having options to compare — rather than a single take-it-or-leave-it offer — makes a meaningful difference.
If your restaurant needs fast access to capital, reach out to Tavrix Capital to explore your options — usually within hours, not days.